Posted by Daniel Bender in Tax: Individual, Estate and Trust, Retirement.
Key points covered in this article:
- Tax, charitable giving, and estate planning decisions are interconnected. Considering them together can help individuals make more informed decisions about their assets, charitable goals, and long-term legacy.
- Timing and asset selection can make a difference. How and when assets are gifted, transferred, or inherited can have different tax implications, making coordinated planning important.
- A coordinated advisory approach can help avoid missed opportunities. Bringing tax, estate, and charitable strategies together can help individuals align financial decisions with both family priorities and philanthropic goals.
An integrated planning approach can help individuals and families align tax efficiency, charitable intent, and legacy objectives.
Many times, tax planning, charitable giving, and estate planning aren’t evaluated as combined financial decisions. In practice, a decision in one area can significantly affect the others.
If you hold appreciated assets or retirement accounts, or if you have charitable or estate-planning goals, an integrated approach can help you manage taxes, support the causes you care about, and preserve wealth for your intended beneficiaries. The key is to evaluate these decisions before transactions occur, while there is still flexibility to choose a more efficient approach.
This planning is especially relevant if you:
- Give to charity regularly
- Hold highly appreciated investments or real estate
- Are approaching retirement or already retired
- Are reviewing or updating an estate plan
It can matter even more in an unusually high- or low-income year, when the timing of income, deductions, gifts, and retirement decisions may produce different tax outcomes.
The central question is not simply, “What should be given?” It is also, “Which assets should be given, to whom, and when?”
Charitable Giving: The Asset Can Matter as Much as the Amount
Two charitable contributions of the same dollar value do not necessarily produce the same tax result. The type of asset used to make the gift can significantly affect the economics of the transaction.
Consider Appreciated Assets Before Automatically Giving Cash
If you hold appreciated investments, contributing an asset directly to charity may offer a different planning opportunity than selling the asset and donating the cash proceeds.
Example: A taxpayer owns $50,000 of stock with a $10,000 cost basis, which represents $40,000 of unrealized appreciation.
Contributing the stock directly may allow the taxpayer to avoid recognizing the embedded capital gain while potentially supporting a charitable deduction based on the stock’s fair market value. This result is subject to applicable limitations, holding-period rules, substantiation requirements, and the taxpayer’s individual circumstances. In many cases, this approach allows the donor to avoid tax on the built-in gain while receiving a charitable deduction for the asset’s full fair market value.
Selling the stock first generally causes the $40,000 gain to be recognized before the cash is contributed.
If you intend to make a charitable contribution and also hold appreciated assets, you may have more than one way to accomplish the same objective. Reviewing your asset mix before making the gift can help determine whether another funding method better aligns your charitable goals with your broader tax strategy.
Qualified Charitable Distributions Can Connect Retirement and Giving Strategies
For eligible IRA owners, a qualified charitable distribution (QCD) is another example of why charitable planning should not be isolated from tax and retirement planning.
Individuals age 70½ and older may be able to transfer funds directly from an IRA to an eligible charity. A qualifying distribution is generally excluded from income and can count toward a required minimum distribution (RMD) when applicable. Because the federal requirements are detailed, they should be reviewed before the transfer is initiated.
QCDs may warrant particular attention for:
- Taxpayers who claim the standard deduction
- Itemizers with significant medical expenses
- High-income retirees
- Individuals monitoring income-related Medicare premium adjustments
In each case, the planning issue extends beyond the charitable deduction alone, because the distribution can affect adjusted gross income (AGI) and your overall tax picture.
For retirees, the effect a gift has on AGI can matter well beyond the deduction itself. Charitable giving should therefore be evaluated alongside IRA distributions, RMDs, taxable income, and other income-sensitive considerations.
Donor-Advised Funds Can Help Align the Timing of Giving and Deductions
Donor advised funds (DAFs) can be useful when the year you claim a deduction does not need to match the year you recommend all your charitable grants. Donated assets are transferred to a sponsoring charitable organization, which then holds legal control over them.
A DAF may be worth evaluating when you want to:
- Make an irrevocable charitable contribution now while recommending grants to charities over time
- In a single tax year, “bunch” several years of giving
- Respond to an unusually high-income year
- Contribute appreciated securities or other noncash assets
The analysis should begin with your charitable intent and your specific facts, rather than with the vehicle itself.
If your charitable intentions are consistent, but your taxable income varies significantly from year to year, you may benefit from reviewing when contributions are made rather than following the same giving pattern annually. Regulatory activity may also affect how these funds operate.
Estate Planning Is Also Asset Planning
An estate plan does more than identify who will inherit property. How assets are titled, which beneficiaries are named on accounts, and which types of assets pass to each beneficiary can all affect administration and taxation.
A basic estate planning review should confirm that the following documents still reflect your current intentions:
- Will
- Durable power of attorney
- Health care directive
- Beneficiary designations
- Any trust arrangements
Primary and contingent beneficiary designations should be reviewed regularly because many assets pass outside of a will.
Common problems include outdated documents, incorrect beneficiary designations, and missing contingent beneficiaries. An otherwise well-designed estate plan can produce unintended results when account registrations and beneficiary designations have not been coordinated with the plan.
Different Assets Can Produce Different Results for Heirs and Charities
If your estate plan includes charitable bequests, deciding which assets to pass to charity, and which pass to family members can be particularly important.
- Traditional IRAs and qualified retirement plans may deserve consideration for charitable beneficiaries.
- Appreciated stock, real estate, tax-free assets, and Roth IRAs may produce different consequences when transferred to heirs.
Estate planning should address more than the percentage of an estate each beneficiary receives. The type of property used to carry out those intentions can affect the ultimate tax consequences.
Understanding Basis in Gifted and Inherited Property
Basis can have a significant effect on the tax consequences of appreciated property. For property received as a lifetime gift, the basis is generally determined using the donor’s adjusted basis and the property’s fair market value.
Inherited property follows different basis rules, with the value generally established using the property’s fair market value when the owner dies, although exceptions may apply. If you are considering a lifetime gift of significantly appreciated property, it is important to evaluate the potential basis implications, not just the asset’s current value.
A decision that appears straightforward from an estate planning perspective can produce different tax results depending on the asset involved and when ownership changes.
Probate Planning Requires More Than a Will
Estate planning also includes evaluating how property will transfer and whether certain assets may pass outside probate. Depending on state law and individual circumstances, mechanisms may include:
- Revocable living trusts
- Joint ownership with rights of survivorship
- Beneficiary designations
- Payable-on-death registrations
- Transfer-on-death deeds for real estate
The appropriate mechanism depends on the asset, ownership structure, family circumstances, and overall estate plan. These techniques should be coordinated with legal counsel rather than implemented in isolation.
State-Specific Considerations: VA, MD, DC & NC
Options for transferring real estate outside probate vary by jurisdiction. Virginia, Maryland, and the District of Columbia permit transfer-on-death deeds for real property, while North Carolina‘s current TOD statutory framework addresses securities rather than providing the same real-property TOD deed mechanism. Property owners should consult estate-planning counsel regarding the options available where their property is located.
Tax Planning Should Happen Before Tax Filing
Tax compliance looks backward. Effective tax planning looks forward. Before year-end, the discussion should focus on what can still be changed. Questions worth considering include:
- Can capital losses offset realized gains?
- Does a lower-income year make a Roth conversion worth evaluating?
- Can income be deferred without creating another problem?
- Should deductions or charitable contributions be accelerated?
- Are estimated tax payments needed?
- Do retirement-plan contributions or annual gifts support the broader plan?
These are planning considerations, not strategies that apply to every taxpayer. Tax preparation looks at what has already occurred, while tax planning looks ahead to identify what can still be changed.
2026 Tax Thresholds Make Timing Important
Understanding where you fall within the current tax structure provides essential context for planning decisions. Under the IRS guidance on the Working Families Tax Cuts for individuals and workers, key federal figures for 2026 include:
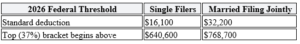
Federal marginal rates range from 10% to 37%.
For retirement savers, the 2026 IRA contribution limit is $7,500. Individuals age 50 and older may make an additional $1,100 catch-up contribution, for a combined limit of $8,600, subject to applicable requirements. Related figures for employer plans are published in the IRS cost-of-living adjustments for retirement plans.
These thresholds are more than annual reference numbers. They provide context for decisions involving the timing of income, deductions, charitable gifts, retirement contributions, and Roth conversions.
The Value of Coordinated Planning
The common thread across these strategies is coordination:
- A charitable gift can affect taxable income.
- An IRA distribution can affect charitable planning.
- A beneficiary designation can affect an estate plan.
- The decision to give appreciated property during life, or retain it, may affect basis and future tax consequences.
A comprehensive planning process brings several areas into the same conversation: current income, gains, losses, deductions, and marginal rates; charitable goals and available assets; retirement accounts and distribution requirements; estate and beneficiary objectives; and timing. The goal is not to pursue every available strategy. It is to identify which choices fit your facts and how one decision may change the result of another.
Planning Before Acting Can Preserve More Options
Many tax, charitable, and estate planning decisions become more difficult to change once a transaction has occurred. Selling an appreciated asset, taking an IRA distribution, transferring property, or leaving outdated beneficiary designations in place can narrow the range of available alternatives.
The practical advantage of reviewing these issues together is that the conversation happens while choices are still available. PBMares can help you evaluate the tax consequences of charitable gifts, retirement distributions, and asset transfer decisions. Our team can also coordinate with your legal and financial advisors when a decision affects estate documents or investment strategy.
To discuss how these considerations may apply to your situation, contact Tax Partner Daniel J. Bender, CPA/PFS, CFP® before implementing a significant charitable gift, asset transfer, retirement distribution, or other major financial decision.
Be sure to consult with your financial or tax advisor on this topic as individual situations may vary. The information contained in this article or webinar, and any related materials, are for informational purposes only, and cannot be relied upon for legal, financial, tax, accounting, or other professional services advice. The content is provided on an “as is” basis and PBMares makes no representations or warranties about the accuracy or sustainability of any information for your purposes. For any specific questions you may have, please contact us.
This content is accurate at the time of publication. Always ensure you are reviewing the most recent information available. Contact your tax or financial advisor if you need clarification.
Contact Us
About the Author
Daniel Bender
CPA/PFS, CFP®
Partner
Fredericksburg
With over 27 years of experience, Daniel has helped clients achieve peace of mind by ensuring that they are fully prepared for their financial future.
View Bio